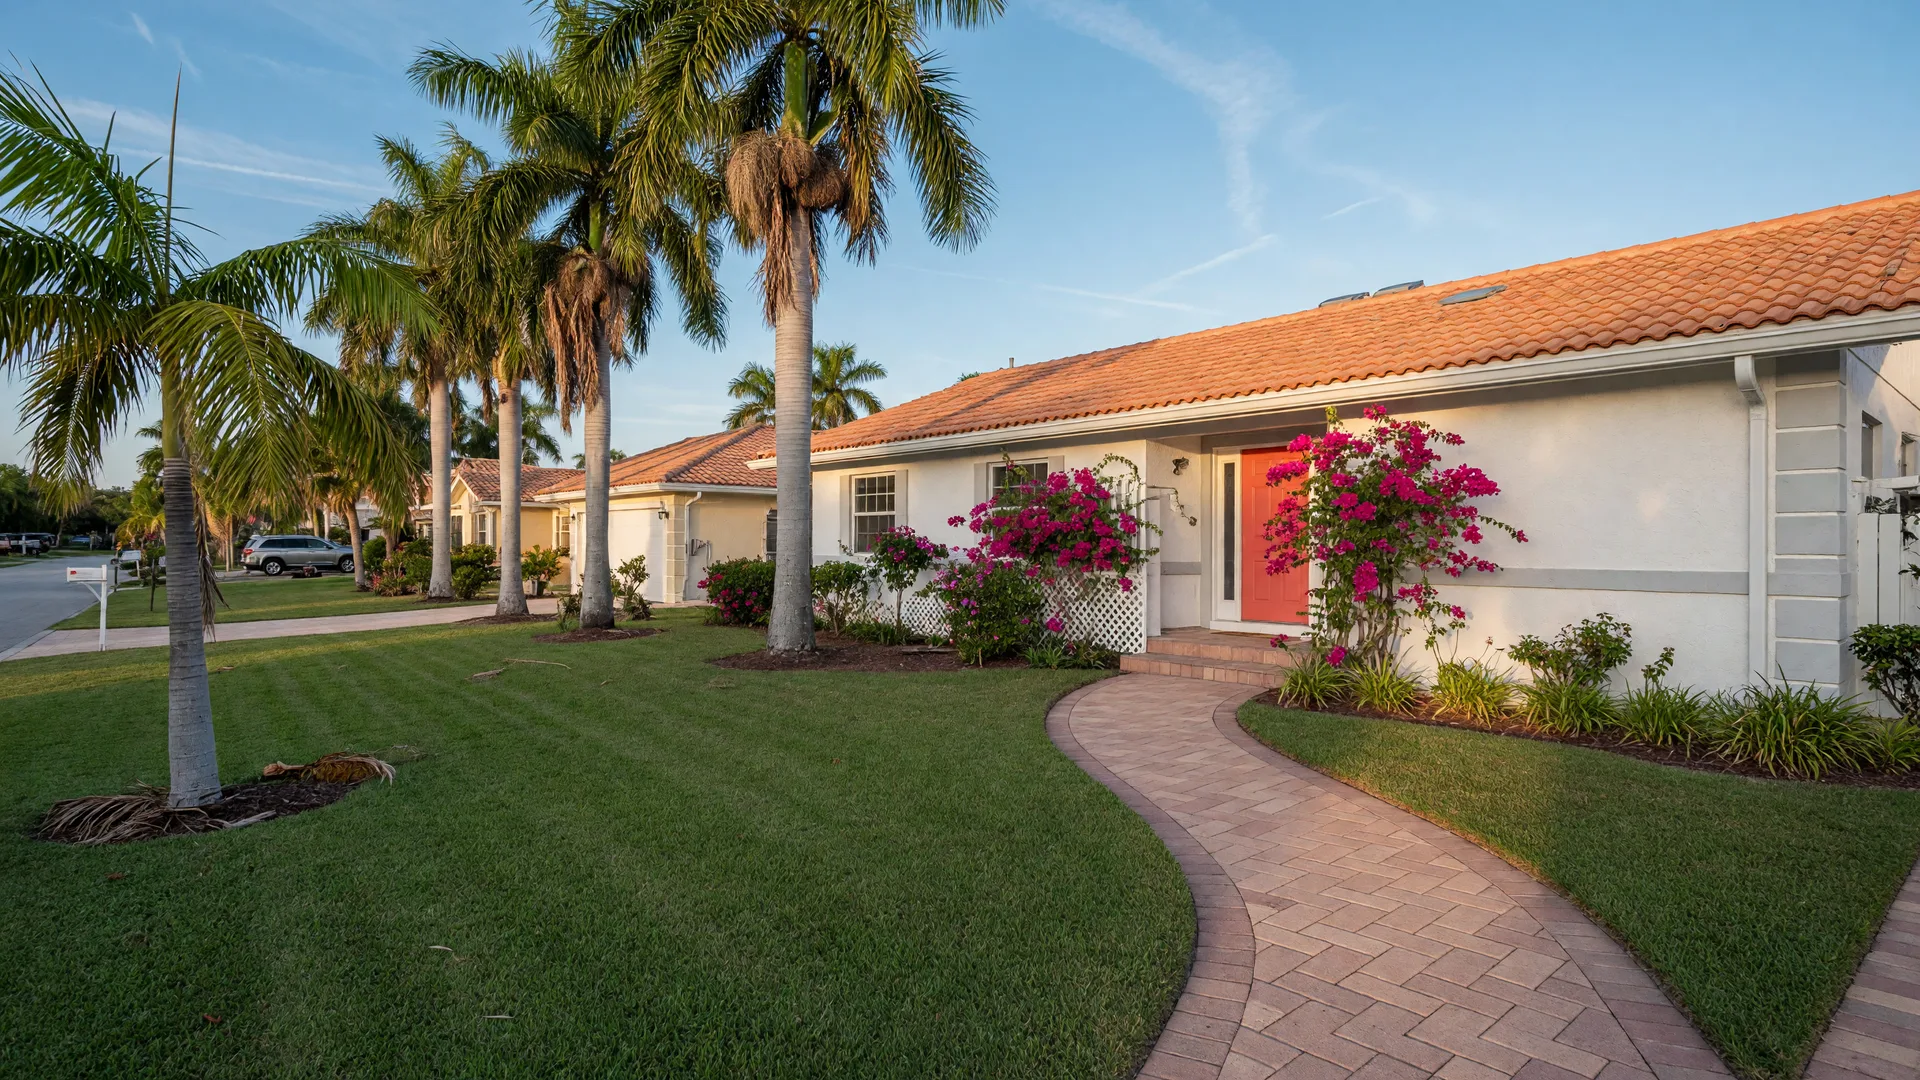
Buying your first home in Naples comes down to a few decisions made in order: get pre-approved, set a budget that fits, and choose a neighborhood where that budget actually works. For a first-time home buyer in Naples, that usually means looking past the waterfront and into condos, townhouses, and single-family homes across the city and the towns around it. This guide covers the real price points, the neighborhoods worth your time, the financing options, and the exact steps from first lender conversation to closing.
If you are also relocating, virtual tours arranged by your agent keep the search moving until you can see homes in person.
Key Takeaways
- Get pre-approved before you look at homes. Your approved amount, not a listing price, sets your budget and makes your offer stronger in a competitive market.
- First-time buyer down payments in Florida can start around 3% with some conventional loans or 3.5% with FHA, with 0% possible for eligible VA borrowers. In many cases, plan on roughly 5% to 8% of the price in total cash once closing costs and prepaids are included, though the total can vary with your loan program and down payment.
- The affordable entry points in the Naples area are often condos and townhomes, plus single-family homes in East Naples, Golden Gate, and parts of Bonita Springs, Estero, and Fort Myers, with some examples below $500,000.
- Budget the whole carry cost, not just the price: HOA dues in a condo community, homeowners insurance, flood insurance where it applies, taxes, and hurricane deductibles are part of the monthly picture.
- Work with one local advisor for the whole process, in English or Spanish, who reviews contracts, negotiates on your behalf, and stays involved through inspection, appraisal, and closing.
What Does a First-Time Home Buyer in Naples Actually Spend?
The honest starting point: pricing in Naples is not uniform across the city. According to the Naples Area Board of REALTORS (NABOR) August 2026 market report, released September 25, 2026, the median closed price was $575,000 for all residential properties, $717,500 for single-family homes, and $417,500 for condominiums, with roughly 622 closed residential sales. Those figures cover the Naples-area MLS in Collier County excluding Marco Island, not solely the City of Naples, and individual neighborhoods and property types vary considerably. The spread between the single-family median and the condo median is a practical reminder that condos and single-family homes require different budgets. The entry tier of the market, where many first-time buyers actually land, sits below those medians. You can track the trend yourself on Zillow's Naples market page.
As examples of the entry tier, condos and townhomes in Collier and Lee Counties have sold in the $300,000s to the $500,000s, and some single-family homes under $500,000 have sold in neighborhoods east of U.S. 41, though current inventory changes month to month. The gap between the waterfront listings everyone sees on social media and the homes that actually work for a first purchase is one of the biggest surprises for buyers who are new to the market.
Where to Look: First-Time Buyer Neighborhoods in Naples
The neighborhoods worth your time depend on what you want to trade off. East Naples and the Golden Gate area, roughly from Radio Road east to Collier Boulevard, hold some of the most realistic entry prices in the city, with condos and modest single-family homes close to shopping and the region's main roads. North Naples, especially east of U.S. Highway 41 in the 34110 and 34120 areas, offers newer construction, Collier schools, and quick access to the highway and the beach when the traffic cooperates.
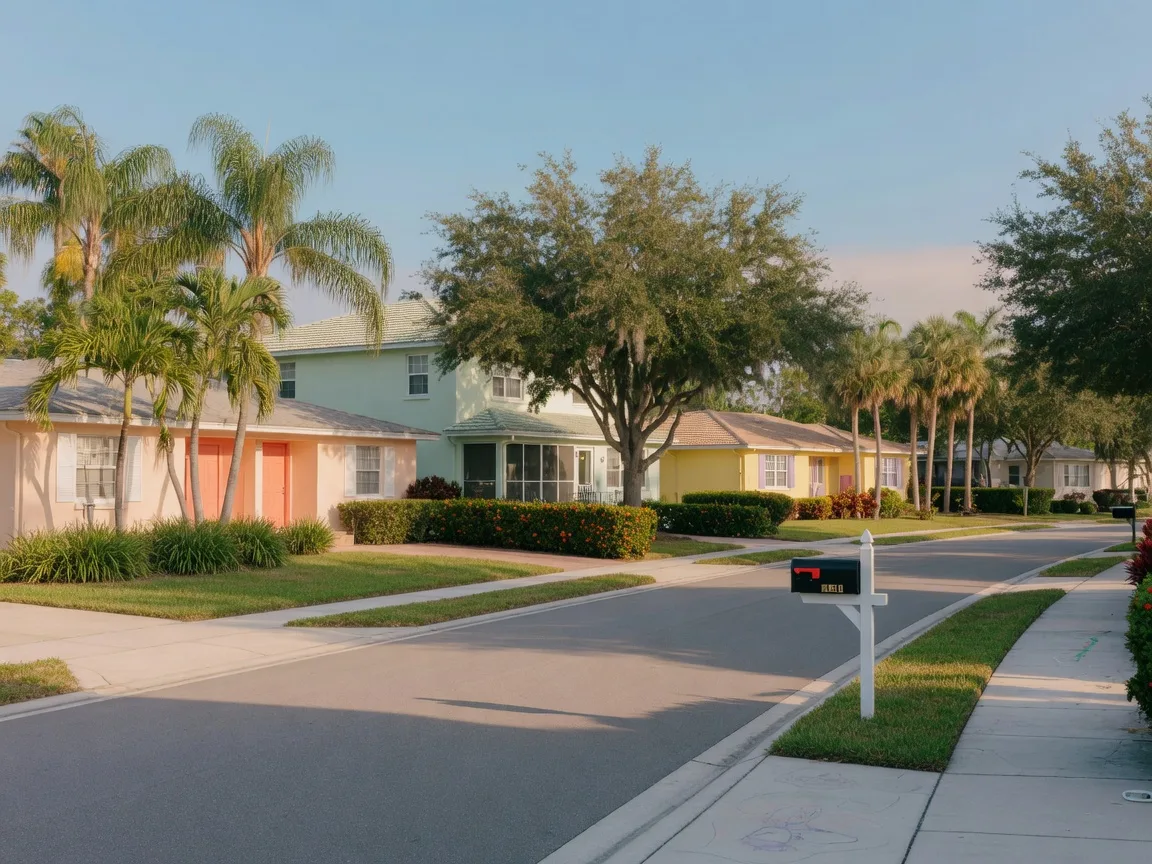
Just north of the Naples city limit, Bonita Springs and Estero pick up where Naples prices thin out: more communities, more new and resale condos, and household incomes that work for first-time buyers, many near Coconut Point and along I-75. Fort Myers keeps the lowest price points in the market, with a healthy mix of condos and affordable single-family homes. If the gulf is your goal, Marco Island is overwhelmingly a condo island and sits at a higher price-per-square-foot, which works when you are ready for that, not usually for a first home.
A neighborhood that wins in real life depends on the rest of your life: your job, your school, and your commute. Families weigh the Collier County Public Schools system, and the district's attendance-boundary tool lets you research school assignments by address, keeping in mind that school zones can change; healthcare workers often weigh a short drive to NCH or the hospitals on Pine Ridge Road. Anyone flying often wants easy access to Southwest Florida International (RSW). The right shortlist is personal, which is why the Naples neighborhood guide walks through each area, city by city.
First-Time Buyer Financing: Down Payments and Your Monthly Payment
You don't need a 20% down payment to become a homeowner. Depending on eligibility, some conventional loans allow as little as 3% down, FHA loans may allow 3.5%, and eligible VA borrowers may qualify for no down payment. A larger down payment can reduce the amount financed and potentially lower mortgage insurance costs. With a conventional loan, putting more down also reduces private mortgage insurance and can help you reach the point where it can be cancelled sooner; FHA mortgage insurance follows different rules. Buyers should compare loan options with a qualified mortgage lender.
Florida also runs state-level programs through Florida Housing that can provide down payment assistance for qualified buyers. The Collier County SHIP Purchase Assistance Program offers interest-free deferred loans of up to $100,000 depending on eligibility and funding, with a maximum purchase price around $793,938 under current program terms. It has income and first-time-buyer requirements, and it is structured as a 30-year deferred, no-payment, no-interest loan secured by a promissory note and a second mortgage. Borrowers must complete a HUD-certified homebuyer education workshop. Florida Housing's Hometown Heroes program can also provide qualifying borrowers up to $35,000 in down payment and closing cost assistance, subject to eligibility and available funding. Program terms and funding change over time, so verify current availability with a participating lender or the county office before you count on a specific amount.
The bigger first-time mistake is budgeting only for the down payment. In many cases, a general estimate for an entry home in the area is roughly 5% to 8% of the purchase price when you count closing costs and prepaid items, though the total can vary with your loan program, your down payment, and your closing date. According to the Consumer Financial Protection Bureau, closing costs alone typically run about 2% to 5% of the purchase price, excluding the down payment. On a $450,000 condo, that kind of estimate leaves you bringing about $22,000 to $36,000 to the table, including down payment, and the exact split depends on your loan and your closing date, which the guide to closing costs in Naples breaks down line by line.
Then the monthly number: principal and interest are only part of it. Buyers in Florida also pay property taxes, homeowners insurance, HOA fees when in a community, and sometimes flood insurance. One tax point matters here: in Florida, a change in ownership generally triggers reassessment, and the previous owner's homestead benefits do not automatically carry over to the new owner, so the new tax bill can be materially higher than what the seller paid. Plan your monthly budget around the expected reassessed amount rather than the seller's current tax bill. Your lender will give you a payment preview; it should always include taxes, insurance, and HOAs, because those three are often the reason a budget falls apart later. For official grounding on the loan basics, the U.S. Department of Housing and Urban Development's buying-a-home guidance walks through the same steps in plain language.
The Naples Home Buying Process, Step by Step
The process here follows the standard Florida contract flow, and knowing each stage before you start removes most of the stress. In short order, these are the six stages the Buying Process covers in detail:
- Get pre-approved first. A lender runs your credit and documents and issues a pre-approval letter with a loan amount. In many cases this takes days rather than weeks, though it can take longer depending on your situation, and it makes your offer real to sellers.
- Shortlist neighborhoods. Pick two or three areas that match your commute, school preferences, and lifestyle, then let pricing in those areas set a realistic search.
- Compare homes and communities. For each condo or house, your agent will research the HOA, its budget, flood zone, and special assessments so you are not surprised later.
- Make a written offer. Strategy and contract terms matter in a market with multiple offers. A seller may counter the price, the closing date, or one of the contingencies.
- Inspect, appraise, reconcile. The home inspection, the lender's appraisal, and your final loan documents line up during the under-contract period, usually 30 to 45 days.
- Close. You sign the closing package, wire the funds, and the title company records the deed with the county. Keys in hand, the process ends at the table you thought it would.
One thing to know before the first tour: under current practice requirements that followed the NAR settlement changes, agents working with buyers generally enter into a written buyer representation agreement before touring properties together, including qualifying live virtual tours. Compensation is negotiable, and the seller may agree to contribute toward buyer-broker compensation. This is a general explanation, not legal advice, so ask your agent to walk you through the agreement before you sign.
You will find a fuller walkthrough, including what to bring to each stage, in our Naples home buyers guide. The one constant we see repeated is that buyers who line financing up early have the calmest moves. First-time buyers are so often stressed only because they start the process out of order.
Condos, Townhomes, or a House: What Do First-Time Buyers Choose?
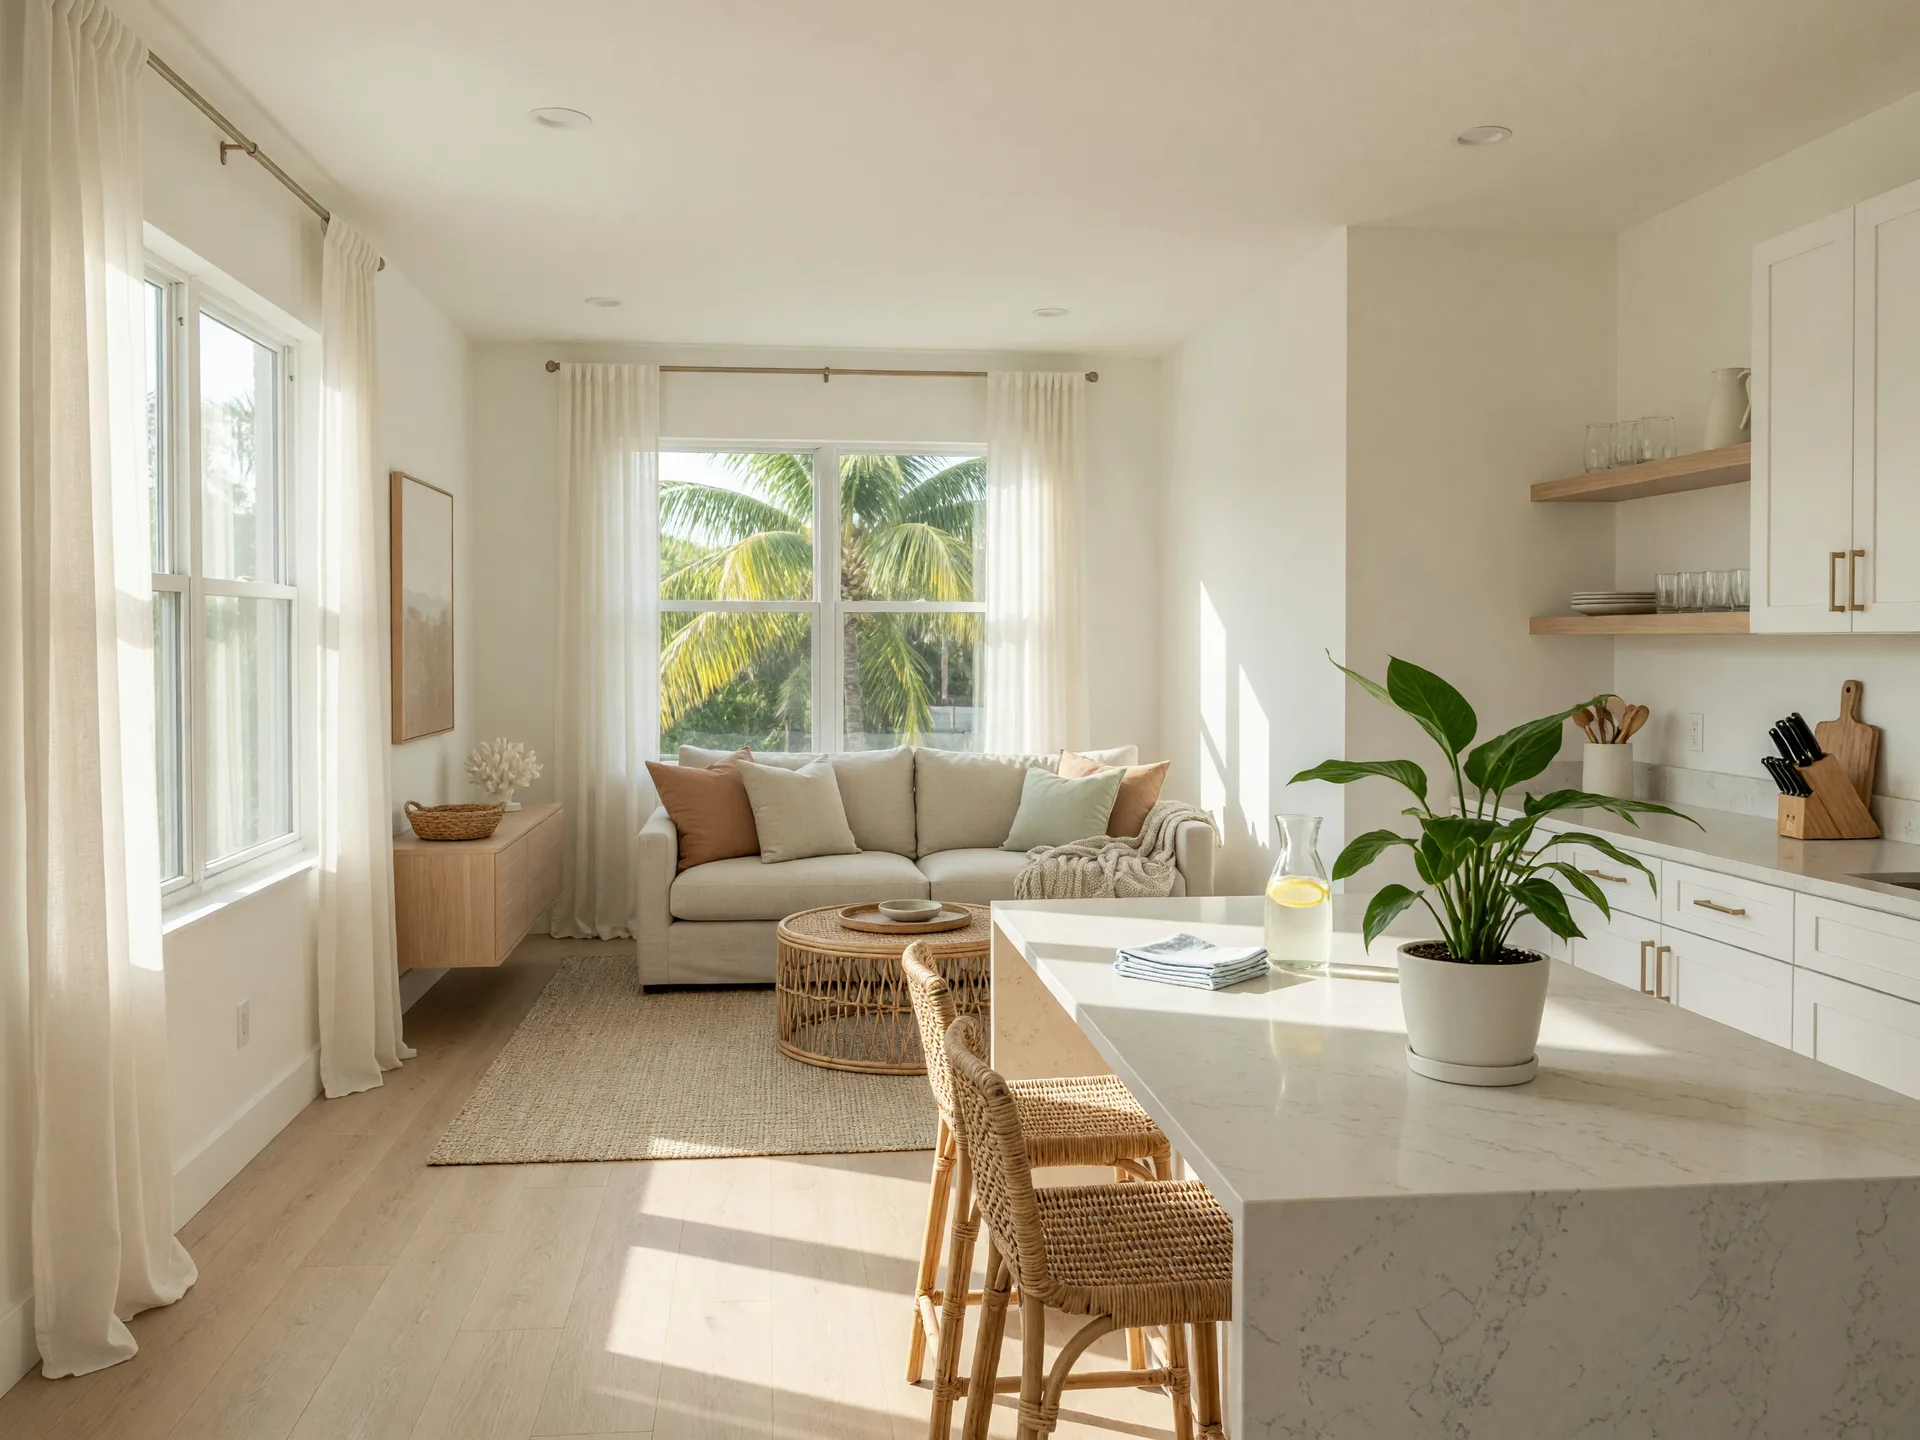
The most common first purchase in Naples is a condo or townhome, and for good reasons: a lower entry price, community amenities like a pool and clubhouse, and an association that handles much of the exterior maintenance. Condos and townhomes can offer attractive entry points into the Naples market, but buyers should carefully evaluate HOA fees, association reserves, insurance coverage, inspection reports, and any pending or anticipated special assessments. Monthly fees can increase, so understanding the community's financial condition is just as important as understanding the purchase price. HOA dues may help fund the condominium association's master policy, but unit owners generally still need their own individual coverage, an HO-6 policy, for the interior of the unit and personal belongings. The trade is the HOA, a real monthly cost and a set of rules, so the guide to buying a condo in Naples is worth reading before you book showings.
Florida law also shapes the condo buying process in ways worth knowing. Covered condominium buildings of at least three habitable stories must maintain structural integrity reserve studies, and certain buildings must undergo milestone inspections. Before you purchase, review the association's available financial records, reserve studies, inspection reports, and assessments. Florida law also provides specific disclosure and cancellation rights for qualifying condominium transactions, so ask your agent what applies to the building you are considering.
A small single-family home gives you a yard, no shared walls, and usually a lower monthly HOA, but it comes with ownership insurance, hurricane-season responsibility, and higher purchase entry in most neighborhoods. There is no universal right answer. The right answer is the one that fits your income, your plans, and your tolerance for repair costs, which is why we always start with the budget conversation instead of the listing search.
Mistakes First-Time Naples Buyers Should Avoid
A few predictable mistakes show up again and again, and all of them are avoidable:
- Skipping the inspection. In Florida, the roof, the AC, and the water heater are consequential, and inspection finds what photos cannot. Do not waive it lightly.
- Underestimating insurance and HOA costs. Get an insurance quote and the HOA's financial statements before you fall in love with a list price.
- Basing your offer only on the list price. Your agent provides a comparable sales report so your offer is grounded in what similar homes actually sold for, not in an emotional reaction.
- Rushing a decision in a multiple-offer moment. Being prepared in advance, funds lined up and inspection contingencies clear, is how you can move quickly without fear.
- Skipping the school and commute check. If you have children, use the district's attendance-boundary tool to research the school assignment and confirm the daily drive before you sign, not after. School zones can change.
How a Bilingual Local Advisor Changes a First Purchase
A first purchase in a market you are still learning is where a local advisor pays for themselves. Catalina Quintero is a REALTOR with The Miranda Group at Premiere Plus Realty, Co., licensed in Florida (SL3635889), and bilingual in English and Spanish. She holds the CIPS, RENE, and ABR designations, and she practiced law before real estate, which shows up in careful contract review and negotiations when the stakes matter most.
Catalina works with first-time buyers across Naples, Bonita Springs, Estero, Fort Myers, and Marco Island, and she serves relocating physicians, international buyers, and veterans moving to the area. If you are buying from another state or another country, the guide for international and Latin American buyers and the guide for relocating physicians walk through the specific questions that come up. For the broader move, the Southwest Florida relocation guide plans the whole transition in order. A plan is only as good as the budget behind it, which is where a first call with Catalina starts.
First-Time Buyer Frequently Asked Questions
How much money do I need to buy a first home in Naples?
In many cases, a general estimate for a low-down-payment purchase is roughly 5% to 8% of the purchase price as your total cash to close, which covers your down payment, closing costs, and prepaid property taxes and insurance, though the total can vary with your loan program and down payment. According to the Consumer Financial Protection Bureau, closing costs alone typically run about 2% to 5% of the purchase price, excluding the down payment. On a $450,000 condo, that kind of estimate works out to roughly $22,000 to $36,000. Down payment minimums in Florida start around 3% for some conventional first-time loans and 3.5% for FHA, with 0% possible for eligible VA borrowers, but closing costs and insurance are paid in addition, so the 5% to 8% total is a useful planning range rather than a fixed rule.
Can I find a first home in Naples for under $500,000?
In many cases, yes. Condos and townhomes under $500,000 have been available in East Naples, North Naples east of the highway, Golden Gate, Bonita Springs, Estero, and Fort Myers, though current inventory changes month to month. The NABOR August 2026 median closed price for all residential properties was $575,000, but the entry tier has also seen sales in the $300,000s to $500,000s. Working with an agent who watches the entry tier daily shows you the realistic inventory much faster than browsing the internet alone.
Is it better to buy a condo or a house first in Naples?
For many first-time buyers in Southwest Florida, a condo or townhome is the practical first step: a lower entry price, HOA-managed maintenance and insurance, and amenities included. The trade-off is a monthly HOA fee and community rules. A single-family home offers more outdoor space and fewer community fees, but a higher entry price and solo responsibility for maintenance. Choose based on your budget, your tolerance for repairs, and what you actually want your weekends to be.
How long does buying a first home in Naples take?
From first conversation to closing, many first-time buyers take about 3 to 6 months total, though some take longer. Pre-approval often takes a few days, and the active search commonly runs 1 to 3 months depending on the market and your price point, but it can take longer. Once your offer is accepted, the under-contract period runs about 30 to 45 days, during which the home inspection, appraisal, financing, and title work all happen. Buyers relocating from out of state are more often on the outer end as they visit in person after virtual search.
Do I need a realtor to buy a first home in Naples?
You are not legally required to use a realtor, but a first-time buyer in a market you are still learning rarely benefits from going alone. A buyers agent covers the local price data, gives you access to the full inventory, negotiates the contract terms, and stays involved through inspection and closing. Find someone bilingual, experienced, and committed enough to explain each step, so you are making decisions with the facts. That is worth more on a first purchase than on any later.
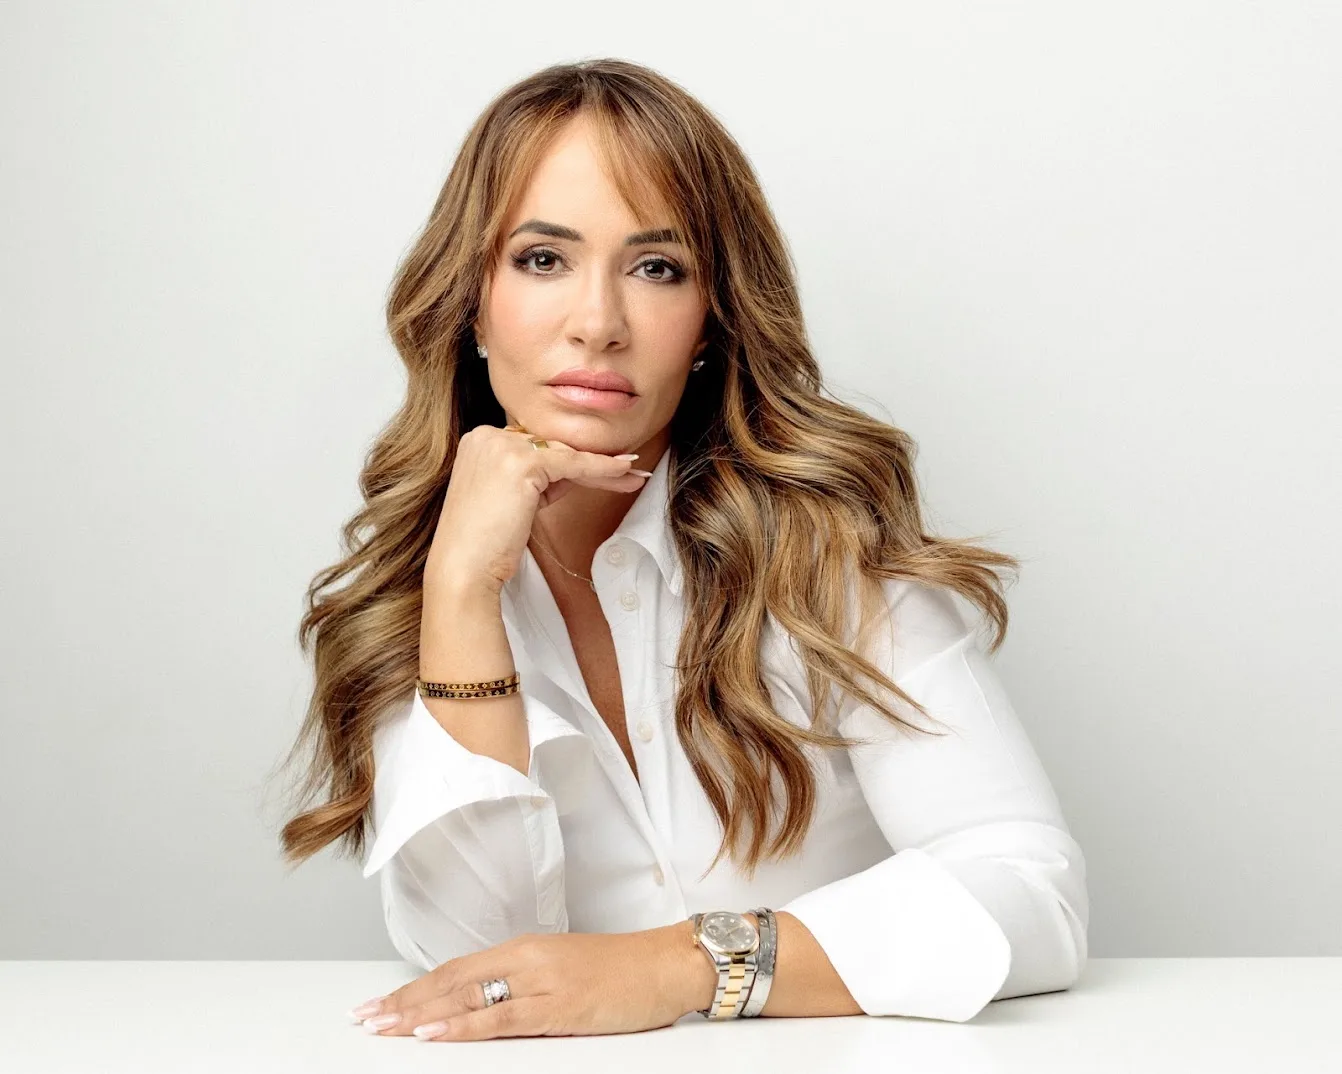
Catalina is a bilingual REALTOR with The Miranda Group at Premiere Plus Realty, Co., serving buyers in Naples, Estero, Bonita Springs, Fort Myers, and Marco Island. She holds the CIPS, RENE, and ABR designations and specializes in guiding local, relocating, and international first-time buyers through the Southwest Florida market, in English or Spanish.
License SL3635889 · Florida
Thinking About a Move to Naples? Start With a Conversation.
Contact Catalina Quintero at (239) 206-6909 or visit catalina-quintero.huzi.site/contact/ to schedule a consultation.